Pay Myself on a Schedule: A Complete Guide for Owners
Pay yourself a steady paycheck from uneven client payments with a schedule that accounts for your business structure, realistic income, taxes, and reserves.
Contents
Paying yourself means regularly transferring money from your business to cover your personal income, using a plan that fits your business structure. Set a realistic amount and schedule, reserve money for taxes and expenses, and keep business and personal accounts separate. Consistent pay and reserves help turn uneven client income into a steadier paycheck without leaving the business short.
Think about the last big client payment that landed in your account. Some of it is already spoken for: software, insurance, and the slow month that’s coming.
The short answer is that you pay yourself a set amount on a set schedule, and treat the rest as business money. That’s how a studio of one turns lumpy client payments into a steady paycheck.
Here we’ll cover how your business structure shapes payouts, how much you can realistically take, what you owe in taxes, and a simple system to keep the money moving.
Why I Need to Pay Myself
It’s easy to pay everyone else first and yourself last, if you pay yourself at all.
Why should you pay yourself first?
Paying yourself first means setting aside a fixed amount for your own pay before the rest of the money gets spent. Four reasons stand out:
- No pay means hobby. If the studio never pays you, it’s a hobby with invoices, however busy the calendar looks.
- Owner is star employee. You’re the most valuable person on the payroll, so you deserve a regular paycheck.
- Prevents resentment. Resentment builds quietly. When clients get paid and you don’t, the work you love starts to feel like a favor.
- Sign of business health. A studio that pays its owner on schedule usually has pricing, invoicing, and cash flow under control.
Think of an illustrator who sends a big campaign’s final invoice, then watches the money vanish into software renewals and a printer bill. Three months later she’s busy and broke, and the work she loved feels like a chore.
So paying yourself first is a priority, not a leftover.
What stops owners from paying themselves
Four patterns usually get in the way:
- Scarcity mindset and fear. Believing there’s never enough makes every draw feel reckless, so the draw never happens.
- Underpricing offers. If your rates don’t cover your own pay along with overhead, there’s nothing left over to pay you.
- Overspending on expenses. Extra gear, subscriptions, and “just in case” purchases quietly eat the money you planned to pay yourself.
- Fear of running out of money. Holding everything back “for safety” keeps cash sitting still while you go without. Safety needs a number, or it keeps growing.
How Your Business Structure Changes Payouts
How you pay yourself depends on how your business is set up. Here’s how the main structures compare.
Taking draws as a solo owner
If you run a single-member LLC, you pay yourself through an owner’s draw: a transfer from the business account to your own. No taxes come out, so you set money aside yourself.
Here’s the catch: your profit counts as personal income whether or not you draw it. A photographer with a strong quarter owes tax on that profit even if it sits in the business account.
A draw reduces owner’s equity (your stake in the business) rather than counting as an expense. It moves cash out of the business without touching profit, so you control the amount and timing.
So what’s the difference between an owner’s draw and a salary for an LLC? A salary runs through payroll with taxes withheld. A single-member LLC owner isn’t an employee of their own company by default, so draws are the usual route.
Paying partners in a multi-owner LLC
Partners generally take draws of their share of profit, generally taxed by ownership percentage whether or not they withdraw it. Some also receive a guaranteed payment: a fixed amount for services or the use of money, paid regardless of profit.
Guaranteed payments show up as an expense on the profit and loss statement (P&L), so they lower profit before the rest is split. Say one partner handles most client work. A guaranteed payment compensates that role without changing who owns what.
Paying yourself a salary in a corporation
A corporation pays you a salary through payroll, then distributions (non-wage payouts of profit). Payroll taxes are withheld from each check, and the company pays its matching share too.
The IRS requires S corporation owners who perform services for the company to receive reasonable compensation as wages before any non-wage distributions.
Woodbury Group’s explainer on reasonable compensation quotes the Form 1120-S instructions on this point.
Your corporation is a separate entity from you, so pay yourself through payroll or distributions, not from the company account whenever cash is tight. Separate on paper, separate in practice.
Check local rules and ask a pro
Rules differ by country, and many places add their own layer on top, so treat these U.S. examples as a starting point. A tax professional or accountant can match your structure to your income and location.
Ask before you pay yourself, not after.
How Much You Can Actually Pay Yourself
Once the money is split, the real question is how much you can count on for yourself. Here’s how we’d size that paycheck.
Splitting revenue into percentages for pay
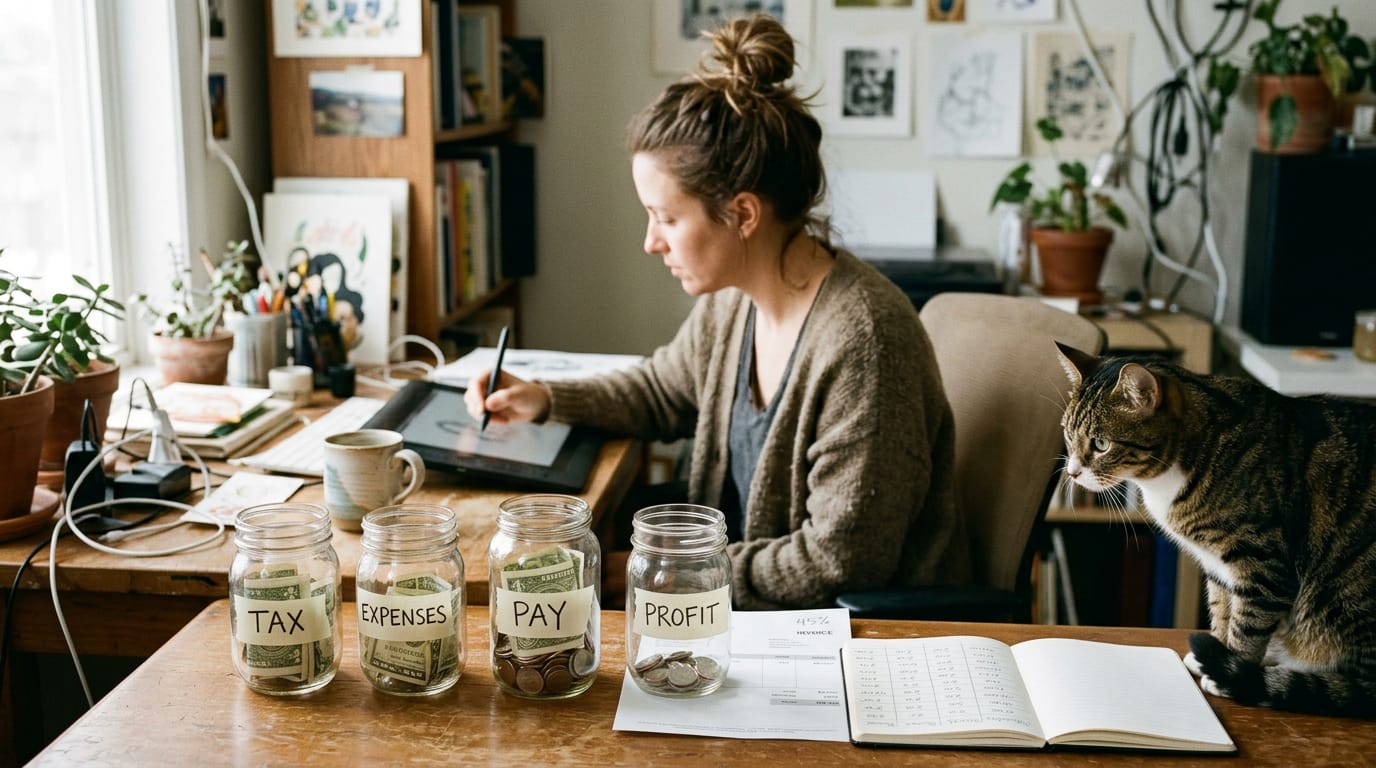
Every dollar gets divided into four buckets:
- Taxes: set aside first, in their own reserve.
- Expenses: capped near 30 to 50% of sales.
- Pay: your owner’s pay share, such as 45%.
- Profit: at least 20% of sales.
For example, a freelance illustrator who bills $8,000 in a month and takes a 45% share sets aside $3,600 as her paycheck. Pay yourself a planned share, not whatever’s left over. Track these percentages monthly so slow months show up early.
Set your day rate to cover that pay. If you need $3,600 a month at 45%, billings must reach $8,000.
Can one person live on $3,000 a month?
It depends on what a single person’s life costs, and your records hold that number.
Total twelve months of personal charges, like rent, groceries, and insurance, then divide by 12 for your baseline.
$3,000 a month is $36,000 a year. Living on $3,000 monthly works when your baseline fits inside it; if it doesn’t, the gap shows what to trim or earn.
Start small and stay consistent. Pay yourself an amount you can hit most months, and raise it after three stable months. Treat $3,000 as a target, not a promise.
Planning pay when income is unpredictable
Start by mapping your revenue on paper: every expected payment, with its due date. Then estimate from your pipeline, the open proposals, weighting each by how likely it is to close.
Hope isn’t a forecast, so check last year’s data, since slow seasons often repeat. Then work backward from your goals to how many paying projects you need.
Consider a photographer with three proposals out, but only one she’s confident will close. She plans pay around that job, so a lost bid doesn’t leave her short on rent.
Weighing growth against your living costs
Every surplus forces a choice: reinvest it in the studio, or cover living costs. Set aside what you’ll owe in taxes first, so a big purchase doesn’t leave a surprise bill.
Your personal expenses set the minimum. A writer eyeing a new laptop checks that floor first, then buys only from surplus, never from rent.
What You Owe in Taxes
Your tax bill depends on how your studio is set up and how you pay yourself, so plan for it before you spend.
Set aside a share for taxes
The biggest tax mistake is treating every dollar as spendable when part of it already belongs to the tax bill. Consider a photographer who spends a big project check, then gets a tax bill as a shock.
With 15% set aside on arrival, that money is already waiting.
You can build a tax reserve by setting part of your revenue aside instead of treating all of it as available to spend. A Michigan Law Review note on dealer reserves describes a reserve account that holds back a portion of each payment.
- Revenue: set aside 15% of every payment you receive.
- Owner’s pay: set aside 30% of what you pay yourself.
- Separate savings account: keep the reserve out of checking.
Keeping it separate matters. A Payroll Taxes and Personal Liability article warns about officers who use funds set aside for the federal government to pay suppliers instead.
How each structure gets taxed
Your structure decides who pays the tax:
- Sole proprietorship: your studio’s profit is taxed on your personal return.
- Partnership: each partner is taxed by ownership share.
- Corporation: payroll tax is withheld from your paycheck, as an employer does.
- Self-employment tax on draws: the tax on the money you take out as a draw, with nobody withholding it for you.
Since nobody withholds tax from your draws, you’ll pay ahead through quarterly estimated tax payments, regular installments made during the year. Waiting for one big bill is the trap.
Ask your accountant which credits you qualify for. A credit cuts your tax bill dollar for dollar, so a yearly review pays off.
Build a System for Paying Yourself
Paying yourself from whatever’s left turns strong months into windfalls and slow ones into nothing. We’d fix that with a few steady habits.
Pay yourself on a steady schedule
Treat your pay as a regular paycheck: a fixed amount on a fixed day. For example, a freelance illustrator sends herself a set amount every Friday, so rent is covered whether or not last week’s invoice cleared.
Start with weekly transfers, which are easier to keep up with while income finds its rhythm. Then automate them so the money moves without a reminder.
A year-end bonus is an option too, once taxes and reserves are covered.
Separate accounts for income, taxes, and pay
It works best with three accounts, each with one job:
- Income and expense account. Client payments land here, and business bills get paid from here.
- Tax and profit savings account. A share of each payment moves here before you’re tempted to spend it.
- Personal account for owner’s pay. Your paycheck comes from this account alone.
Set money aside on purpose, not by hoping there’s enough left.
How does paying yourself first work?
Paying yourself first means moving your share out of each payment before bills or spending come out. You pay yourself first, and expenses share what’s left.
Three common methods put it into practice:
- Profit First: a named method that sorts each payment into accounts for profit, owner’s pay, taxes, and expenses.
- Envelope system: each bill or goal gets a labeled envelope, physical or digital, and you spend only what’s inside.
- Bucket budgeting: income goes into named buckets, like bills, taxes, and pay, and each covers only its purpose.
Build reserves for slow and lumpy months
A three-month reserve covers your pay and essential bills for about three months if work dries up. Build a six-month emergency fund over time for longer gaps.
In strong months, save first, before a big payment turns into extra spending. When nothing comes in, your paycheck comes from the reserve, and the transfer keeps running as the balance drops.
Smoothing lumpy project income means paying yourself from your average income, not your best month.
A writer with one big June contract and two small August jobs, for instance, moves June’s surplus into reserves and pays herself from them in August, so her paycheck stays level.
Keep clean records and the right tools
Clean records mean knowing your numbers, not guessing at them. Log every payment and expense with a date and a short note. A spreadsheet is enough to start, and accounting software saves time as transactions pile up.
If bookkeeping crowds out design or photography work, consider outsourcing it to a bookkeeper. The goal is audit-ready financial statements: records a tax preparer can follow without a long back-and-forth.
Keep personal and business money separate. Don’t pay personal bills from the business account, or the reverse. Guesswork isn’t a system.
Paying yourself on purpose means choosing a number, a schedule, and a tax set-aside before the money arrives. Do that, and the lumpy months don’t feel like emergencies anymore. You still have slow weeks, but they no longer decide when you get paid.
Pay yourself on purpose, and the business finally works for you.
References
- Taxation - Income Tax — repository.law.umich.edu
- Payroll Taxes and Personal Liability — digitalcommons.fiu.edu (1993)
- Reasonable Compensation — woodburytaxgroup.com
Questions
What is the difference between an owners draw and a salary for an LLC?
For a single-member LLC taxed by default, an owner's draw is a transfer from business funds to the owner, not a payroll expense, and no taxes are withheld. A salary is paid through payroll with taxes withheld; the owner of a default single-member LLC generally is not an employee of the LLC. Tax treatment can differ if the LLC elects corporate tax status.
What are the biggest tax mistakes business owners make?
Common tax mistakes include spending money that should be reserved for taxes, failing to make required estimated tax payments, and mixing personal and business finances. Business owners may also misclassify their pay or overlook credits and deductions they qualify for. Keep records, separate tax savings, and ask a tax professional about obligations for your business structure.
How do I pay my self?
Choose a set amount you can afford and transfer it on a regular schedule from your business account to your personal account. First reserve money for taxes and business expenses, and keep enough cash for slow months. The right method depends on your structure: a single-member LLC owner typically takes draws, while a corporation pays owner-employees through payroll.
How does pay yourself first work?
Pay yourself first by moving a planned amount from incoming business money into your personal pay account before spending the remainder. Reserve taxes and assign money for expenses and profit as part of the system. A fixed schedule and separate accounts can make the transfers consistent.
Why should you pay yourself first?
Paying yourself first makes your income more predictable, helps prevent resentment from working without regular pay, and makes your personal pay a business priority rather than whatever is left over. It can also encourage sound pricing and cash-flow habits. Set an amount the business can sustain and keep taxes and essential expenses in view.
Can a single person live on $3,000 a month?
It depends on your location, housing costs, insurance, and other expenses. $3,000 a month is $36,000 a year; compare that amount with a full year of personal costs divided by 12 to see whether it meets your baseline. If it falls short, the difference shows how much you may need to reduce expenses or increase income.
Sources
- Reasonable Compensation | Woodbury Group, LLC, woodburytaxgroup.com
- Taxation - Income Tax - Accurabilty of Dealer Reserves Withheld by Finance Company, repository.law.umich.edu
- Payroll Taxes and Personal Liability, digitalcommons.fiu.edu,